Roof Financing Options
Roof Financing in Omaha, NE
A roof can't always wait for the savings account to catch up. We'll help you understand every financing path — from home equity to contractor plans — so you can protect your home now.
Call Now: (402) 216-8850
Why It Matters Here
Why Roof Financing Matters in Nebraska
Nebraska roofs don't fail on a convenient schedule. A single hail or wind event can turn a roof you planned to replace in five years into one you need to replace this month. That timing rarely lines up with a fully funded savings account.
Insurance helps, but it rarely covers everything. Deductibles come out of your pocket, and policies that pay actual cash value (ACV) rather than replacement cost can leave a meaningful gap between the check and the actual cost of the work.
Financing closes that gap. It lets you protect your home immediately — before water and weather cause far more expensive damage — and spread the cost into manageable payments. Below, we break down every major option honestly, including the trade-offs of each.
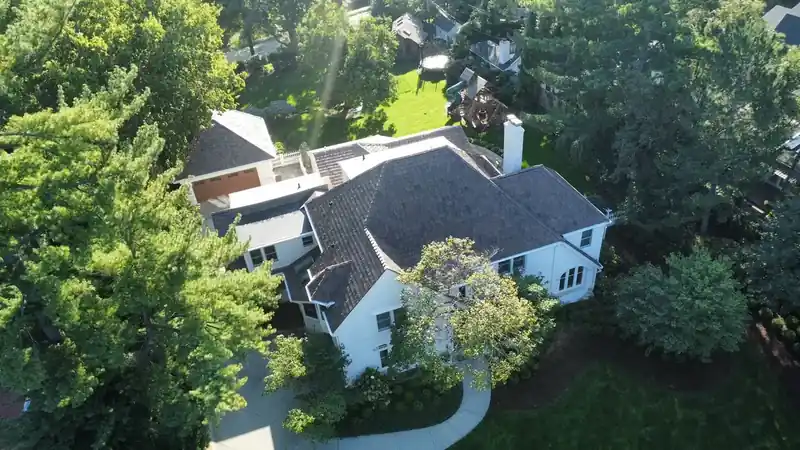
Omaha homeowners typically finance a roof through one of several paths: a HELOC, a home equity loan, contractor-arranged financing, a personal loan, insurance bridge financing, or a credit card for smaller projects. The best choice depends on your equity, credit, timeline, and how sensitive you are to interest rate and payment structure.
Using Home Equity
Home Equity Financing
If you have built equity in your home, these are often the lowest-cost paths.
Home Equity Line of Credit (HELOC)
A revolving line you draw against as needed, secured by your home. Rates are usually variable, interest may be tax-deductible (consult your tax advisor), and lenders typically require you to retain 15-20% equity (an 80-85% loan-to-value limit). Flexible, but the variable rate means payments can rise.
- Revolving, draw as needed
- Typically variable rate
- Possible tax deductibility
- Requires 80-85% LTV
Home Equity Loan
A fixed-rate lump sum repaid on a predictable schedule, also secured by your home. You know the rate and payment for the life of the loan, which makes budgeting simple. It does require an appraisal and a closing process, so funding is not instant.
- Fixed rate, lump sum
- Predictable payments
- Appraisal required
- Slower to fund than alternatives
Other Paths
Financing Without Tapping Equity
When you lack equity, need speed, or are bridging an insurance claim.
Contractor-Arranged Financing
Financing arranged through the roofer's lending partners, often with fast (same-day) approval. Structures range from standard installments to deferred-interest and promotional 0% periods of 12-24 months. Watch the fine print: if a deferred-interest balance is not paid off in the promo window, interest can be charged retroactively. Always confirm the total cost of the loan.
Personal Loans
Unsecured loans that fund quickly and don't put your home on the line. Because they are unsecured, rates run higher than equity products. A solid fit for homeowners with limited equity who still want fast, predictable fixed payments.
Insurance Bridge Financing
When a claim is approved but the payout is still in process, bridge financing lets you start repairs immediately and apply the insurance proceeds when they arrive. This keeps storm damage from worsening while the paperwork catches up.
Credit Card Financing
Best reserved for smaller projects or when you have a 0% promotional offer you can pay off in the window. For full replacements, carrying a revolving balance at standard card rates is usually the most expensive option — use with caution.
What You're Investing In
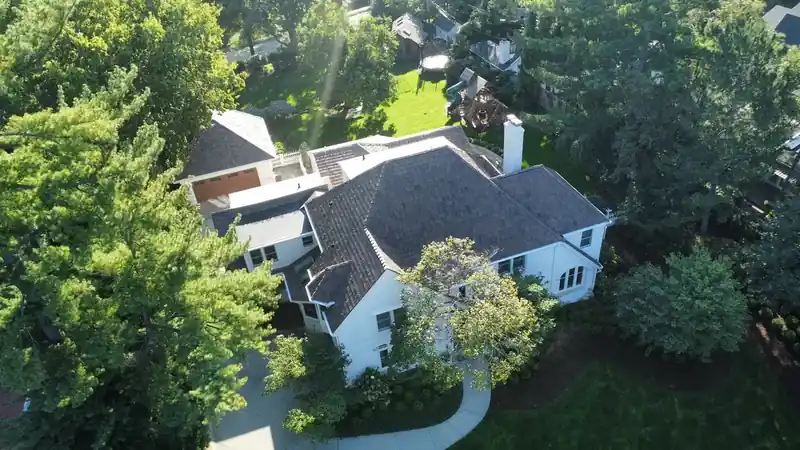
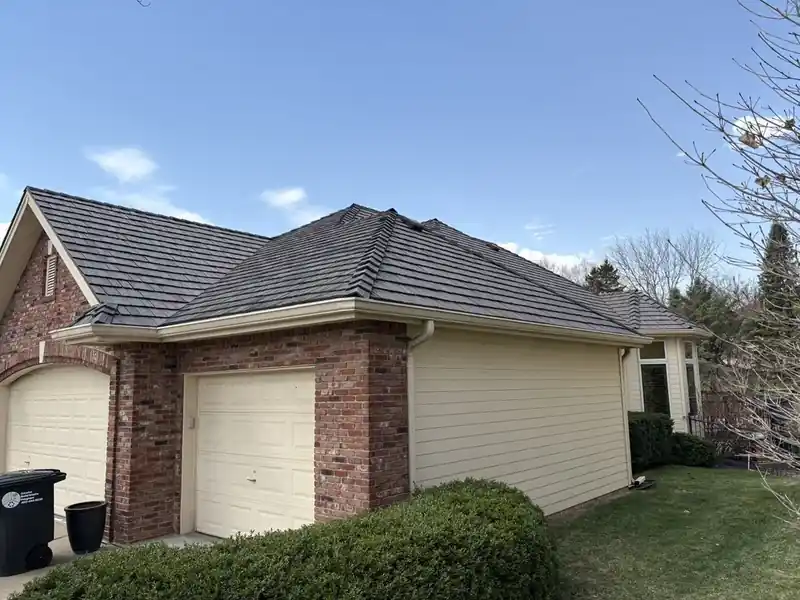
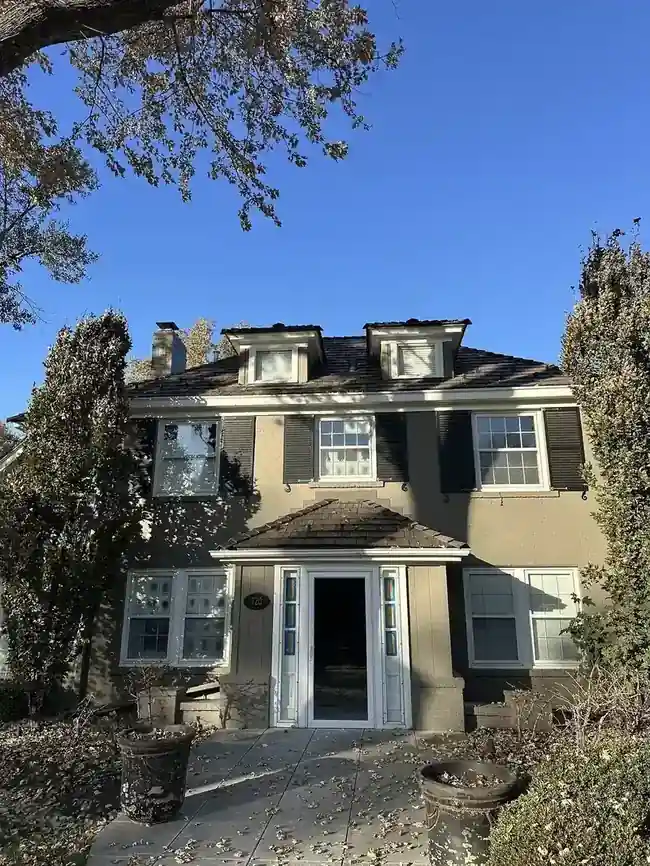
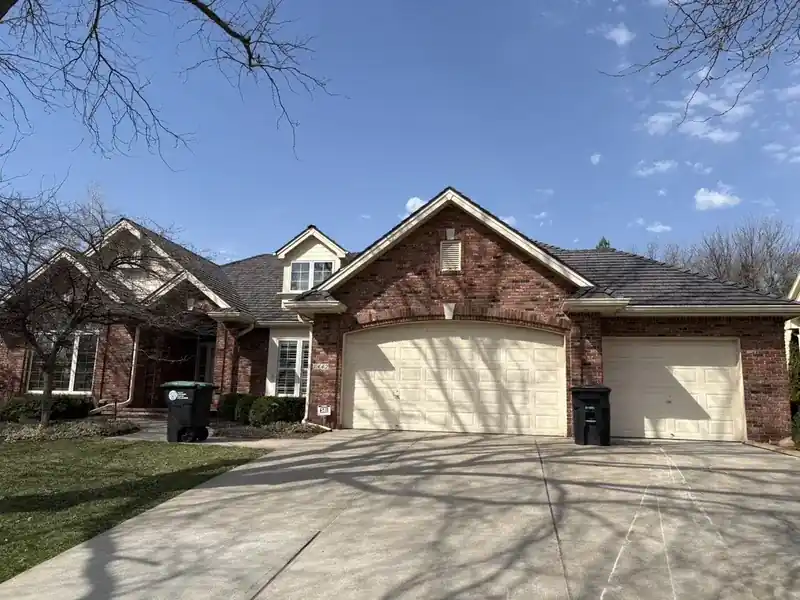
Roofs We've Helped Omaha Homeowners Fund
Financing makes projects like these possible without waiting for savings to catch up.
We'll Help You Choose, Not Pressure You
There is no single right way to finance a roof — only the option that fits your equity, credit, timeline, and comfort with rate and payment structure. Our role is to lay out the choices honestly, including the catches, so you can make a confident decision.
Start with a free, no-obligation estimate. Once you know the scope and the number, we'll walk through the financing paths available to you and help you move forward in whatever way makes the most sense for your household.
Explore Our Services
Frequently Asked Questions
Let's Find a Way to Fund Your Roof
Get a free estimate and a straightforward walkthrough of your financing options. No pressure — just a clear path forward.
Serving Omaha, Papillion, Bellevue, La Vista, Elkhorn, Gretna, and surrounding areas